Home Equity Loans & Lines of Credit Put the home you've worked hard for to work for you, with a team right here in your community.
Your home's equity is the difference between what your home is worth and what you still owe on it. ACNB Bank offers two ways to borrow against it: a home equity loan, which gives you one lump sum at a fixed rate, and a home equity line of credit (HELOC), which lets you draw money as you need it, up to an approved limit.
Apply OnlineLimited Time Offers
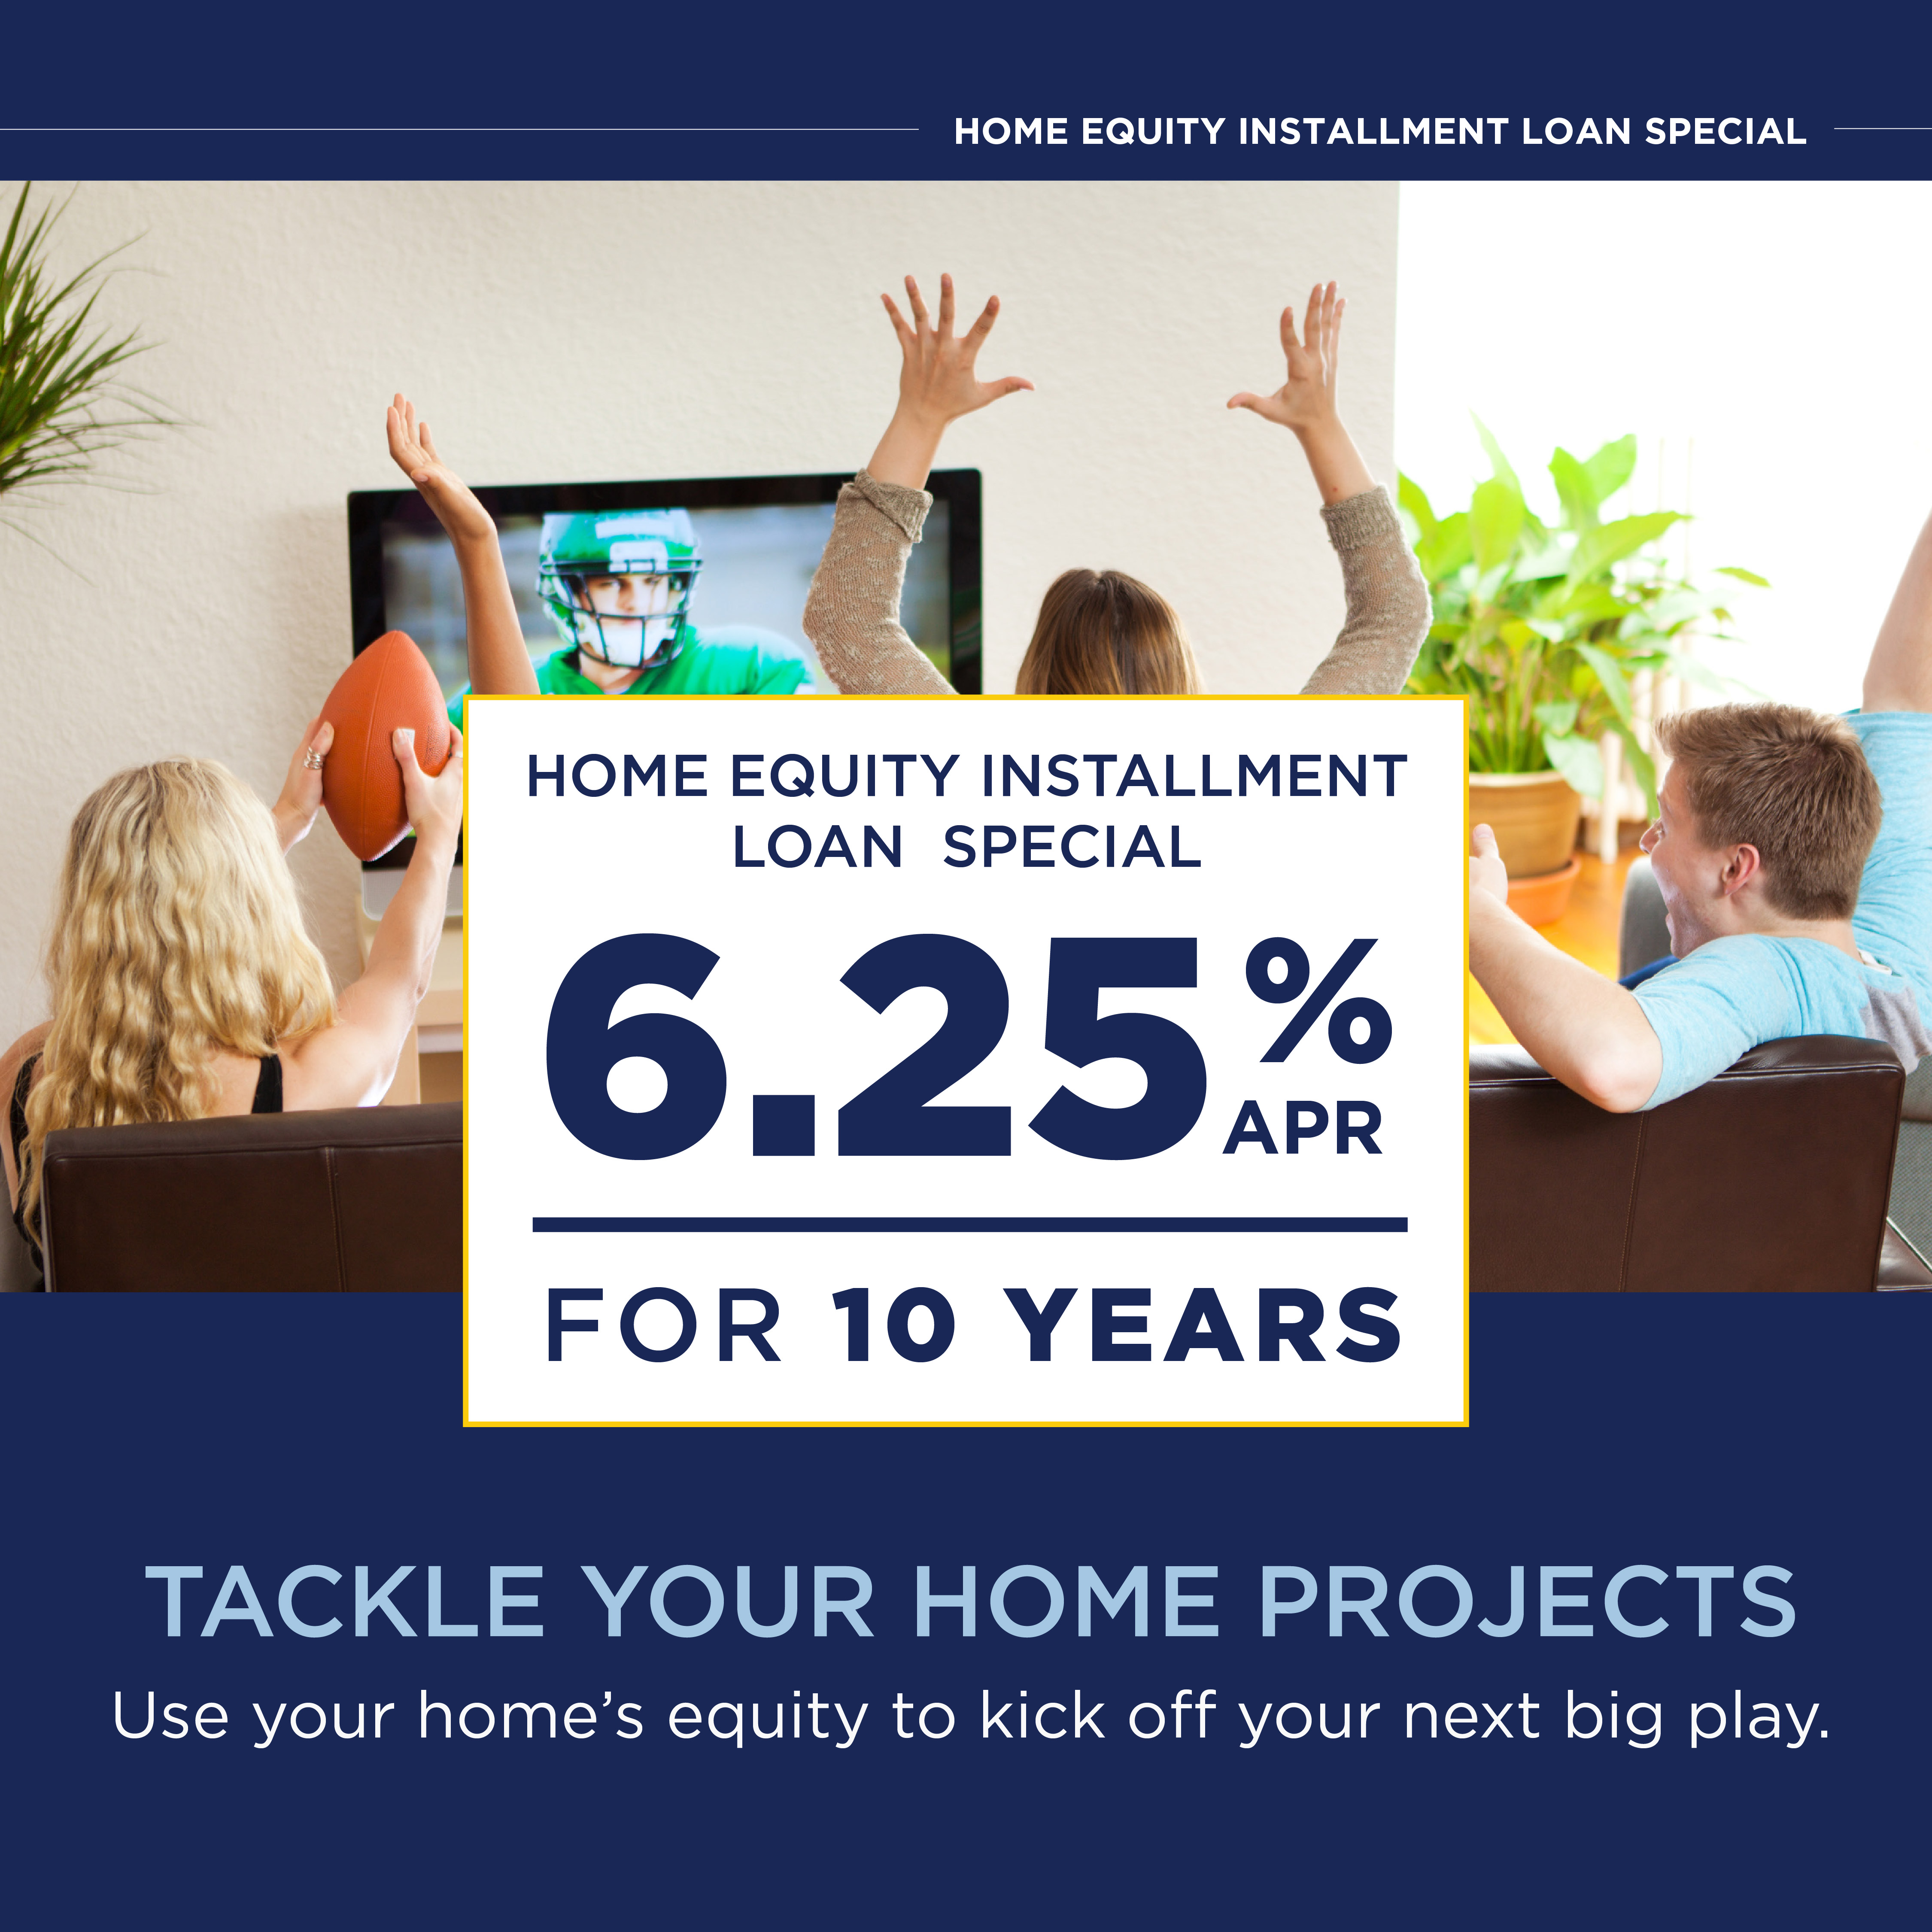
Home Equity Installment Loan Special*
- Home Equity installment loan of 10 years with an APR of 6.25% when the loan payment is automatically debited from a qualifying Traditions Bank checking or statement savings account.
- Establish at least one recurring direct deposit of $500 or more limited to payroll, Social Security, qualified retirement plan distributions, or other government benefits into the qualifying account at least four business days prior to closing.
- Have the loan payment automatically debited from the qualifying Traditions Bank account.
- See offer details here.
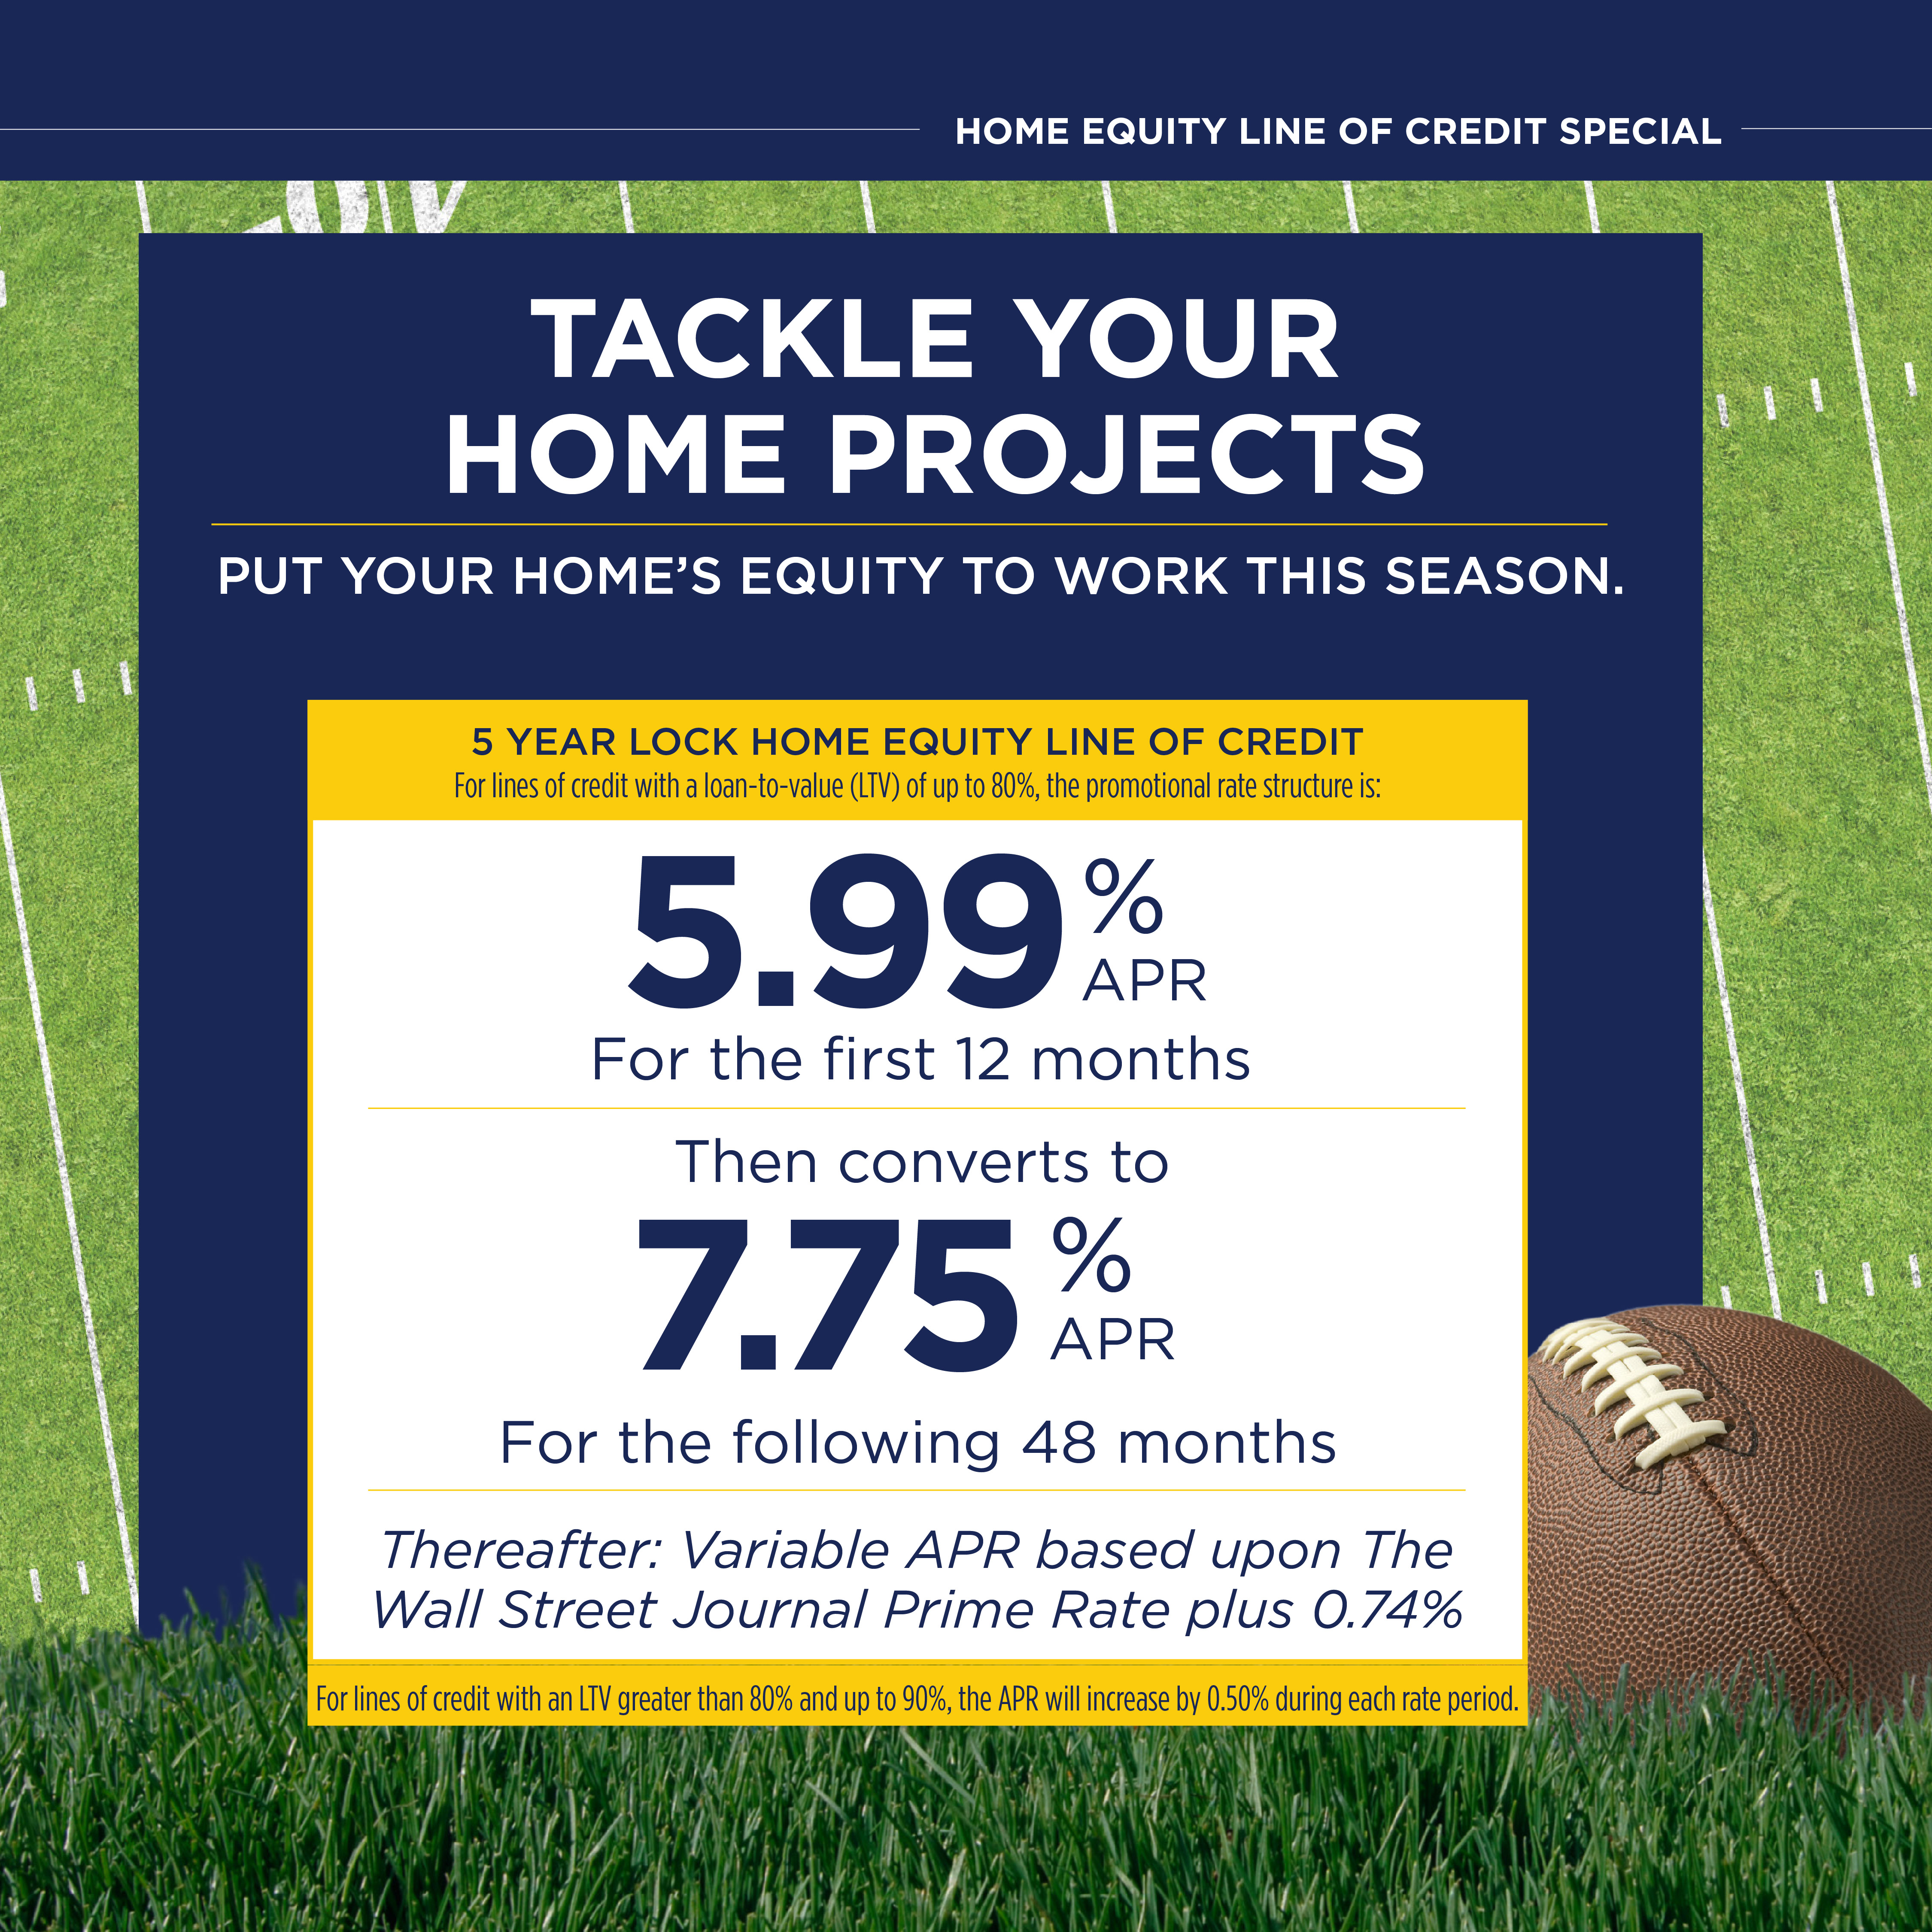
Home Equity Line of Credit Special†
- 5 Year Lock Home Equity Line of Credit
- For lines of credit with a loan-to-value (LTV) of up to 80%, the promotional rate structure is:
- 5.99% APR for the first 12 months
- Then converts to 7.75% APR for the following 48 months
- Thereafter: Variable APR based upon The Wall Street Journal Prime Rate plus 0.74%
- For lines of credit with an LTV greater than 80% and up to 90%, the APR will increase by 0.50% during each rate period.
- See offer details here.
Two Ways To Use Your Home's Equity
Both options are secured by your home and can help with renovations, paying off higher-interest debt, tuition, and life's bigger expenses. The difference is how you receive the money and how you pay it back.
Home equity loan
- Terms available up to 20 years
- Borrow as little as $3,500
- Payments come out automatically from your Traditions Bank account
Home equity line of credit (HELOC)
- Pay your balance down and borrow again during your draw period
- Borrow as little as $5,000
- Access your funds when you need them
Not sure which one fits your plans?
If you know what your project will cost and want one steady payment, a home equity loan is worth a look. If the costs will come in over time, or you're not sure yet what you'll need, a line of credit may give you more room.
Our guide covers the rest: how each one works, what to ask about fees and closing costs, and the questions worth asking before you apply.
How It Works
1. Apply
Apply online anytime, or stop by your local Community Banking office.
Lending decisions are made locally, by our team who knows your community.
3. Close near home
Sign your paperwork with the team at your local Community Banking office.
4. Put your equity to work
Receive your lump sum, or start drawing on your line of credit.
Home Equity Questions We Hear Often
-
How much can I borrow?
It depends on your home's value, what you still owe on your mortgage, and your credit. The minimum amount to borrow for a home equity loan is $3,500, while the minimum amount for a home equity line of credit is $5,000.
-
Will this change my mortgage?
No. Your mortgage stays exactly as it is. A home equity loan or line of credit is a separate account secured by your home, with its own payment.
-
Is the interest tax-deductible?
It may be, if you use the money to buy, build, or substantially improve your home. Tax situations vary, so talk with your tax advisor before counting on a deduction.
-
Do I need a Traditions Bank checking account?
No, but having one helps. Customers with a Traditions Bank checking account may qualify for a lower rate and reduced fees, and Advantage Rewards and Advantage Rewards Plus customers receive a credit toward closing costs.
Our Checking Accounts -
How long does it take to get my money?
The timeline varies depending on the type of home equity product and the information needed to process the application. In most cases, the process takes a few weeks from application to closing. Your lender will keep you informed throughout the process and let you know if any additional information is needed.
-
Can I pay it off early?
Yes. You can pay off your loan or line of credit at any time, though certain products may be subject to an early termination fee. Ask our team what applies to yours.
Have questions? We're here to help.

Call Us
Our Customer Contact Center can answer your questions about home equity loans and lines of credit.
Monday through Friday
8 a.m. to 6 p.m.
Saturday
8 a.m. to 1 p.m.

Email Us
Send us a note and someone from our team will get back to you. Please don't include account numbers or other confidential information in an email.

Visit an Office
Our Community Banking team lives and works where you do, across south central Pennsylvania and northern Maryland. Our team of experts are here to assist.
Resources

Calculators
Run the numbers before you decide. Estimate a monthly payment, compare what consolidating your debt could save you, and see how soon you could pay it off.

Rates
Check out all of our current rates.
*HOME EQUITY INSTALLMENT FIXED-RATE LOAN 10 YEARS (HEIL)
APR = Annual Percentage Rate. Effective 09/8/2026 – 11/30/2026. Offer and effective dates are subject to change without notice. Promotional rates are based on the applicant's creditworthiness. All loans and rates are subject to credit approval and standard underwriting criteria. Property must be located within ACNB Bank's approved service area. Contact ACNB Bank for eligible counties and markets. The loan must be secured by the borrower's owner-occupied principal residence. A minimum of $10,000 in new money is required. Payoffs of existing debt with ACNB Bank are not considered new money. The minimum loan amount is $10,000.
Promotional Relationship Rate
A promotional APR of 6.25% is available for loans with a loan-to-value (LTV) of up to 80%. For loans with an LTV greater than 80% and up to 90%, the applicable APR will increase by 0.50%.
To qualify for the promotional relationship rate and promotional fee waivers, the applicant must:
- Have or open an ACNB Bank checking or statement savings account;
- Establish at least one recurring direct deposit of $500 or more limited to payroll, Social Security, qualified retirement plan distributions, or other government benefits into the qualifying account at least four business days prior to closing;
- Have the loan payment automatically debited from the qualifying ACNB Bank account
With an APR of 6.25%, the monthly loan payment is $112.29 for each $10,000 borrowed for a term of 120 months.
Promotional Fee Waivers and Credits
For applicants meeting the promotional relationship requirements above, ACNB Bank will pay or waive the following fees, as applicable:
- Flood Certification
- Lien Search
- Automated Valuation Model (AVM)
- Property Condition Report (PCR)
- Mortgage Recording Fee
- Wire Transfer Fee, if funds are disbursed by wire
- Up to $5,000 in Maryland recordation taxes for properties located in Maryland
If ACNB Bank is unable to determine the property's value using an Automated Valuation Model (AVM) and Property Condition Report (PCR), an appraisal may be required.
Eligible borrowers will also receive a lender credit of $100 toward appraisal costs. Advantage Rewards and Advantage Rewards Plus checking customers will receive a lender credit of $200 toward appraisal costs instead of the $100 lender credit. Appraisal credits may not be combined.
Title insurance is required for loan amounts over $400,000. When required, title insurance is the applicant's responsibility and is not included in the promotional fee waiver.
Reimbursement of Bank-Paid Closing Costs
If the loan is paid off within 36 months of closing, the borrower will be required to reimburse ACNB Bank for applicable closing costs paid or waived by the Bank in connection with the loan, subject to applicable law.
Non-Relationship Promotional Rate
A promotional APR of 6.45% is available to qualifying applicants who do not meet the relationship requirements above when the loan is secured by the borrower's owner-occupied principal residence and the LTV is 80% or less.
For loans with an LTV greater than 80% and up to 90%, the applicable APR will increase by 0.50%. Other rates and terms are available.
Member FDIC. Equal Housing Lender.
† 5 YEAR LOCK - HOME EQUITY LINE OF CREDIT
APR = Annual Percentage Rate. Effective 09/8/2026 – 11/30/2026.
Offer and effective dates are subject to change without notice. Promotional rates are based on the applicant's creditworthiness. All loans and rates are subject to credit approval and standard underwriting criteria. Property must be located within ACNB Bank's approved service area. Contact ACNB Bank for eligible counties and markets. Property insurance is required. A minimum of $10,000 in new money is required. Payoffs of existing debt with ACNB Bank are not considered new money. The minimum loan amount is $10,000.
Promotional Rate
For lines of credit with a loan-to-value (LTV) of up to 80%, the promotional rate structure is:
- First 12 months: 5.99% APR
- Following 48 months: 7.75% APR
- Thereafter: Variable APR based upon The Wall Street Journal Prime Rate plus 0.74%
For lines of credit with an LTV greater than 80% and up to 90%, the APR will increase by 0.50% during each rate period.
Accordingly, for LTVs greater than 80% and up to 90%:
- First 12 months: 6.49% APR
- Following 48 months: 8.25% APR
- Thereafter: Variable APR based upon The Wall Street Journal Prime Rate plus 1.24%
As of September 17, 2026, The Wall Street Journal Prime Rate was 7.00 %, resulting in a variable APR of 7.74% for LTVs up to 80% and 8.24% for LTVs greater than 80% and up to 90%. The maximum APR is 18.00%.
Payment must be automatically deducted from an ACNB Bank checking or statement savings account.
Your minimum payments may not be sufficient to fully repay the principal outstanding on your line at the end of the term. If the minimum payments are not sufficient to repay the outstanding principal, you will be required to pay the remaining outstanding balance amortized over 120 months.
For non-Maryland properties, the prepayment penalty for home equity lines of credit terminated in the first 36 months is 2% of the credit limit or $350, whichever is less.
Promotional Fee Waivers
To qualify for the promotional fee waivers, the applicant must:
- Have or open an ACNB Bank checking or statement savings account; and
- Establish at least one recurring direct deposit of $500 or more limited to payroll, Social Security, qualified retirement plan distributions, or other government benefits into the qualifying account at least four business days prior to closing;
For applicants meeting these requirements, ACNB Bank will pay or waive the following fees, as applicable:
- Flood Certification
- Lien Search
- Automated Valuation Model (AVM)
- Property Condition Report (PCR)
- Mortgage Recording Fee
- Wire Transfer Fee, if applicable
- Up to $5,000 in Maryland recordation taxes for properties located in Maryland
Appraisal Costs
If ACNB Bank is unable to determine the property's value using an Automated Valuation Model (AVM) and Property Condition Report (PCR), an appraisal may be required. Eligible borrowers will receive a lender credit of $100 toward appraisal costs. Advantage Rewards and Advantage Rewards Plus checking customers will receive a lender credit of $200 toward appraisal costs instead of the $100 lender credit. Appraisal credits may not be combined.
Title Insurance
Title insurance is required for line amounts over $400,000. When required, title insurance is the applicant's responsibility and is not included in the promotional fee waiver.
Reimbursement of Bank-Paid Closing Costs
If the line of credit is paid off and closed within 36 months of opening, the borrower will be required to reimburse ACNB Bank for applicable closing costs paid or waived by the Bank in connection with the line of credit, subject to applicable law. Other rates and terms are available.
Member FDIC. Equal Housing Lender.